News
Delhi High Court Draws the Line on “Source”: A Win for Teva on Cross-Border Taxability
17 Sep 2026
- DMD Advocates
- Matter Reporting
The Delhi High Court has delivered a significant ruling in a batch of connected writ petitions filed by Teva Pharmaceutical Industries Ltd. (Israel) and Teva Pharmaceuticals USA Inc., before a Division Bench of Justice Dinesh Mehta and Justice Vinod Kumar.
A settlement between the Teva and Ranbaxy groups over ANDA and 180-day exclusivity rights for generic Atorvastatin in the US led Ranbaxy India to remit Rs. 1,851 crore to Teva Israel, after deducting tax at source. Teva Israel approached the AAR seeking a ruling that the receipt was business profit, and hence not taxable in India under the Act or the India-Israel DTAA. The AAR declined the application, calling the arrangement a ploy to avoid tax.
Core question: Could a payment from Ranbaxy India to Teva Israel be treated as income accruing or arising in India when the underlying contracts were executed and worked out entirely in the United States?
Findings:
- Section 5(2)(b) has no default source rule. The Revenue conflated the source of the payment with the source of the income -the payer being Indian doesn’t, by itself, convert a remittance to a non-resident into income arising in India. There must be a real nexus with India, or the receipt must fall within a deeming provision.
- The deeming fiction under Section 9 is exhaustive – limited strictly to what Parliament enumerated. This receipt fits neither Section 5(2)(b) nor Section 9.
- The right to tax is a right of exaction, not a right of exclusion. Income escaping tax elsewhere doesn’t, by itself, create a basis to tax it in India.
- The AAR overstepped its jurisdiction under Chapter XIX-B. Having declined to rule on the very question of taxability referred to it, it couldn’t simultaneously find sham, collusion and avoidance -based on its own assessment of the parties’ commercial choices and foreign law. The ruling was set aside, the Section 245Q application allowed, and the payment held not taxable under the Act.
- Reassessment proceedings against Teva USA were quashed.
- Protective assessment has legal recognition; protective recovery does not.
- Withholding refunds for over a decade was held arbitrary to the point of being confiscatory. The Revenue directed to refund Rs. 783 crore, with interest, within two months, subject to a corporate guarantee/solvent security from Teva USA.
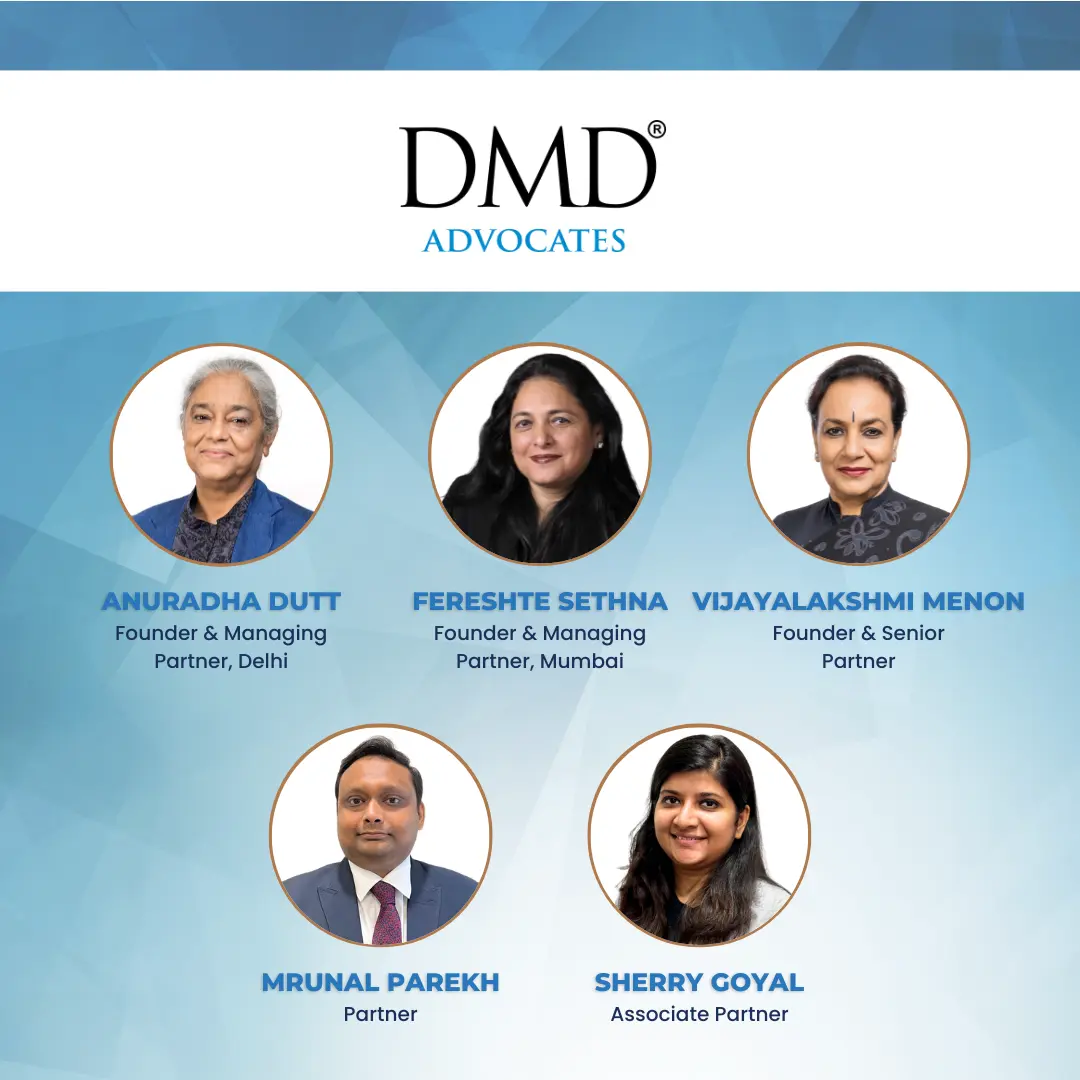
Teva Pharmaceuticals USA Inc. was represented by Senior Advocates Harish N Salve and Sachit Jolly, along with DMD Advocates led by Anuradha Dutt, Founder & Managing Partner, Delhi, Sherry Goyal, Associate Partner, Viyushti Rawat, Counsel, Raghav Dutt, Senior Associate, and Devansh Jain, Associate.